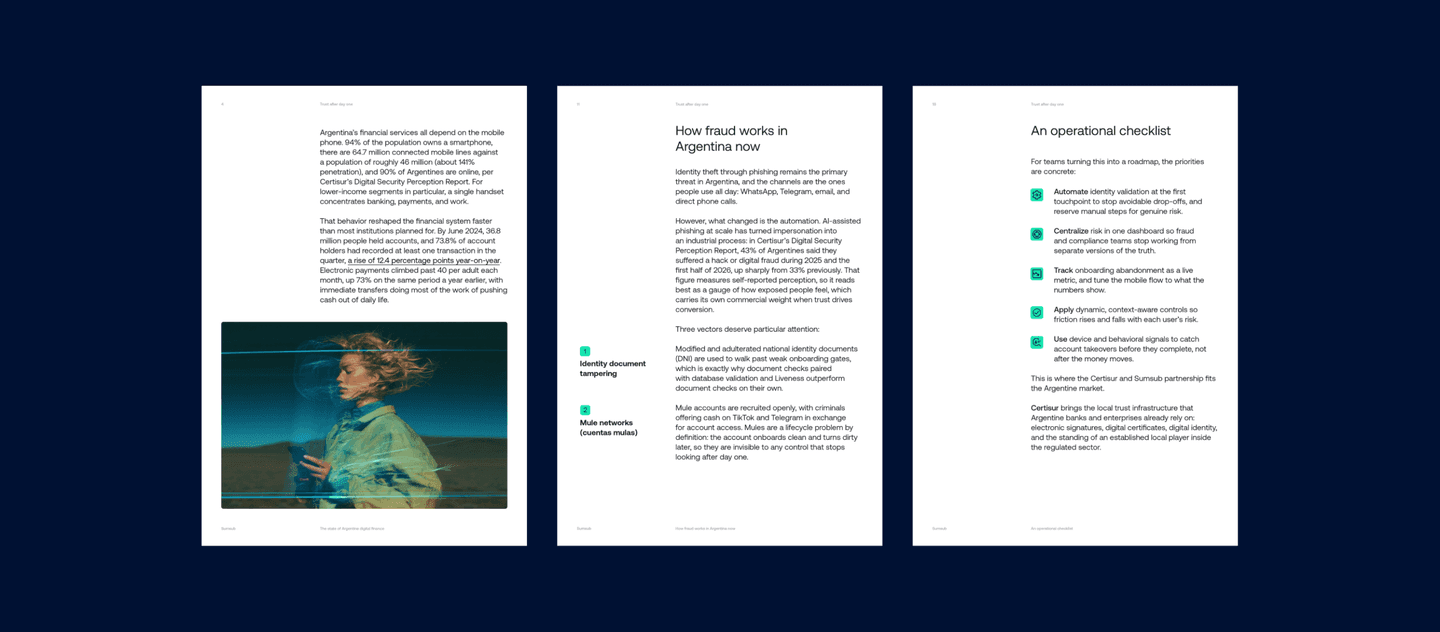
Argentina digitized faster than its verification infrastructure. 94% of the population owns a smartphone, electronic payments have climbed past 40 per adult a month, up 73% year-on-year, and more than 8.1 million people now hold fintech credit, close to 4 in 10 formal borrowers. That growth runs on small tickets and thin margins: the average fintech loan to an individual is ARS541,394, compared with more than ARS4.1 million at a traditional bank. The new borrowers are younger and mobile-first.
Onboarding is only day one. Fraud in Argentina is automated and AI-assisted, and 43% of Argentines report suffering a hack or digital fraud during 2025 and the first half of 2026, up from 33% a period earlier. The local vectors are specific: adulterated identity documents at the front gate, cuentas mulas recruited for cash on TikTok and Telegram, AI-assisted phishing over WhatsApp, and manipulated devices slipping past static checks.
This report works through what verification across the entire customer journey looks like in Argentina, drawing on Certisur's local trust infrastructure of electronic signatures, digital certificates, and digital identity, and on Sumsub's verification, fraud prevention, transaction monitoring, and Travel Rule layer.
What you'll learn:
- Where conversion and trust leak on one-time onboarding, across stacked validation steps, manual document uploads, image-quality demands, and forced channel switching
- Why onboarding is day one of a continuous relationship, and what that changes about how a verification flow is built
- How non-document verification confirms low-risk users in seconds, and when a risk-based journey should trigger document validation and biometric liveness
- How fraud operates in Argentina now, across DNI tampering, cuentas mulas on TikTok and Telegram, AI-assisted phishing, and device and session manipulation
- Why legacy core banking, missing APIs, and siloed identity, fraud, and authentication tools stall modernization, and what one connected platform changes
- What full-lifecycle monitoring catches after onboarding, from mule networks to account takeovers, shown by a LATAM payments and crypto business running the model at 18 seconds per check and a 99% pass rate, plus a five-point operational readiness checklist
This report is for: digital banking leaders, fraud prevention and risk operations teams, compliance officers and MLROs, digital transformation directors, and customer onboarding product managers at banks, fintechs, insurers, and regulated digital commerce in Argentina, particularly teams scaling mobile-first onboarding and disbursement at volume.